Short sales, South Placer market trends, mortgage rates, ranch property and three featured homes.ALEX DYER | REAL ESTATEPLACER & SACRAMENTO COUNTIES · SEPTEMBER 24, 2026This week's market

Dated: August 16 2023
Views: 114
The rising cost of just about everything from groceries to gas right now is leading to speculation that more people won’t be able to afford their mortgage payments. And that’s creating concern that a lot of foreclosures are on the horizon. While it’s true that foreclosure filings have gone up a bit compared to last year, experts say a flood of foreclosures isn’t coming.
Take it from Bill McBride of Calculated Risk. McBride is an expert on the housing market, and after closely following the data and market environment leading up to the crash, he was able to see the foreclosures coming in 2008. With the same careful eye and analysis, he has a different take on what’s ahead in the current market:
“There will not be a foreclosure crisis this time.”
Let’s look at why another flood is so unlikely.
One of the main reasons there were so many foreclosures during the last housing crash was because relaxed lending standards made it easy for people to take out mortgages, even if they couldn’t show that they’d be able to pay them back. At that time, lenders weren’t being very strict when assessing applicant credit scores, income levels, employment status, and debt-to-income ratio.
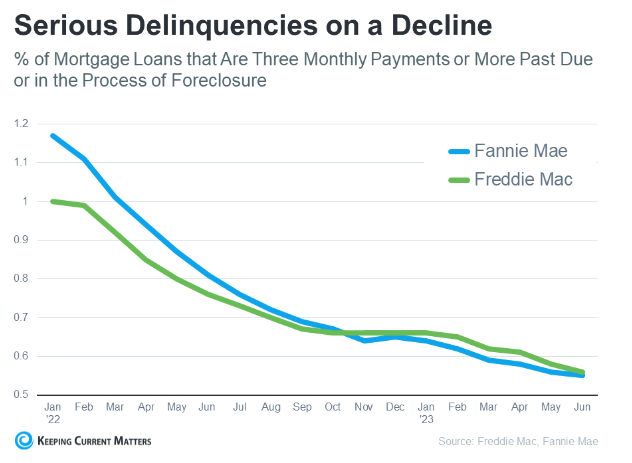
But now, lending standards have tightened, leading to more qualified buyers who can afford to make their mortgage payments. And data from Freddie Mac and Fannie Mae shows the number of homeowners who are seriously behind on their mortgage payments is declining (see graph below):
Molly Boese, Principal Economist at CoreLogic, explains just how few homeowners are struggling to make their mortgage payments:
“May’s overall mortgage delinquency rate matched the all-time low, and serious delinquencies followed suit. Furthermore, the rate of mortgages that were six months or more past due, a measure that ballooned in 2021, has receded to a level last observed in March 2020.”
Before there can be a significant rise in foreclosures, the number of people who can’t make their mortgage payments would need to rise. Since so many buyers are making their payments today, a wave of foreclosures isn’t likely.
If you’re worried about a potential flood of foreclosures, know there’s nothing in the data today to suggest that’ll happen. In fact, qualified buyers are making their mortgage payments at a very high rate.
If you're in the market for a home, you can trust the experienced professionals at eXp Realty of California. We are dedicated to providing superior service and expertise to help you achieve your real ....
Short sales, South Placer market trends, mortgage rates, ranch property and three featured homes.ALEX DYER | REAL ESTATEPLACER & SACRAMENTO COUNTIES · SEPTEMBER 24, 2026This week's market
Sacramento Housing Market • Distressed Property ReportSacramento Short Sales Are Rising in 2026 — Here’s What the Numbers Really ShowShort sales are showing up again nationally and
Weekly Market Report · South Placer CountyRoseville, Rocklin & Lincoln Real Estate Market ReportWeek of September 17 – 23, 2026 · Prepared by Alex Dyer, Your
Living in Placer CountySearch land and ranch listings Book a callLand & Ranch Guide, September 2026How Much Acreage Do You Need? Sizing Your Dream Ranch PropertyStart with the life you want, not
Additional:
915 Highland Pointe Dr. Ste 250Should you require assistance in navigating our website or searching for real estate, please contact our offices at 916-318-3487.
CA License # 01239383

 All measurements and all calculations of area are approximate. Information provided by Seller/Other sources, not verified by Broker. All interested persons should independently verify accuracy of information. Provided properties may or may not be listed by the office/agent presenting the information. Data maintained by MetroList© may not reflect all real estate activity in the market.
All real estate content on this site is subject to the Federal Fair Housing Act of 1968, as amended, which makes it illegal to advertise any preference, limitation or discrimination because of race, color, religion, sex, handicap, family status or national origin or an intention to make any such preference, limitation or discrimination.
MetroList CA data last updated: September 27, 2026 6:34 AM UTC Terms of Use.
Vendor data provided by Inside Real Estate, LLC.
